The Importance of Updating Your Estate Plan Regularly
August 23, 2023

As life evolves, so do our priorities, relationships, and assets. One thing that should evolve along with these changes is your estate plan. It's easy to think of estate planning as a one-time task, but the reality is that life is full of twists and turns.


How Often Should You Update Your Estate Plan?


While there's no one-size-fits-all answer, a good rule of thumb is to review your estate plan every three to five years. That being said, certain life events should trigger an immediate update, such as marriage, divorce, the birth or adoption of a child, significant changes in your financial situation, or the purchase of new property. Consider any of these milestones as a signal to reach out to an experienced Vermont estate planning attorney without delay.


Life's Changes Demand Adjustments


Think about how much can change in a few years – a new addition to the family, a career change, or a substantial shift in your financial situation. These life events can have a significant impact on your estate plan. For instance, if you've recently welcomed a child, you'll want to ensure that your will reflects your wishes for their guardianship. Similarly, if you've acquired new assets or properties, it's essential to make sure they're accounted for in your plan.


Legal Changes and Tax Implications


Vermont's legal landscape, just like any other, is subject to change. Tax laws, inheritance regulations, and other legal matters can evolve over time. Failing to update your estate plan to align with these changes could lead to unintended consequences. Regularly reviewing and updating your plan with the guidance of experienced legal professionals ensures that your documents remain in compliance with current laws, avoiding complications in the future.


Protecting Your Family's Interests


Estate planning isn't just about assets; it's also about your loved ones' well-being. If your family situation has changed due to marriage, divorce, or the blending of families, your estate plan should reflect these new dynamics. Regular updates can ensure that your assets are distributed as you intend, even if your family structure has evolved over time.


Addressing Health and Incapacity Concerns


A comprehensive estate plan includes not only a will but also documents like a living will and power of attorney. These documents become critical in the event of unexpected health challenges or incapacitation. As your health status or your preferences regarding medical care may change, it's essential to revisit and update these documents regularly so they reflect your current wishes.


Ensuring a Smooth Transition


One of the primary goals of estate planning is to make the transition easier for your loved ones when the time comes. Without updated documents, your beneficiaries might face unnecessary legal hurdles and delays, creating stress during an already difficult time. Regularly reviewing and updating your estate plan minimizes the chances of these complications and ensures a smoother transition for your heirs.


Contact Deppman Law PLC for Your Estate Planning Needs


When it comes to protecting your assets and the well-being of your loved ones, regular estate plan updates are essential. At Deppman Law PLC, we understand the unique needs of Vermont residents, and we're here to help you navigate the estate planning process with ease. Lesley and Benj are committed to crafting plans that reflect your current situation and future goals. Whether you're experiencing life changes or want to ensure that your existing plan remains up-to-date, we are here to provide tailored guidance and peace of mind. Contact us today for a confidential consultation and to learn more.
September 15, 2026
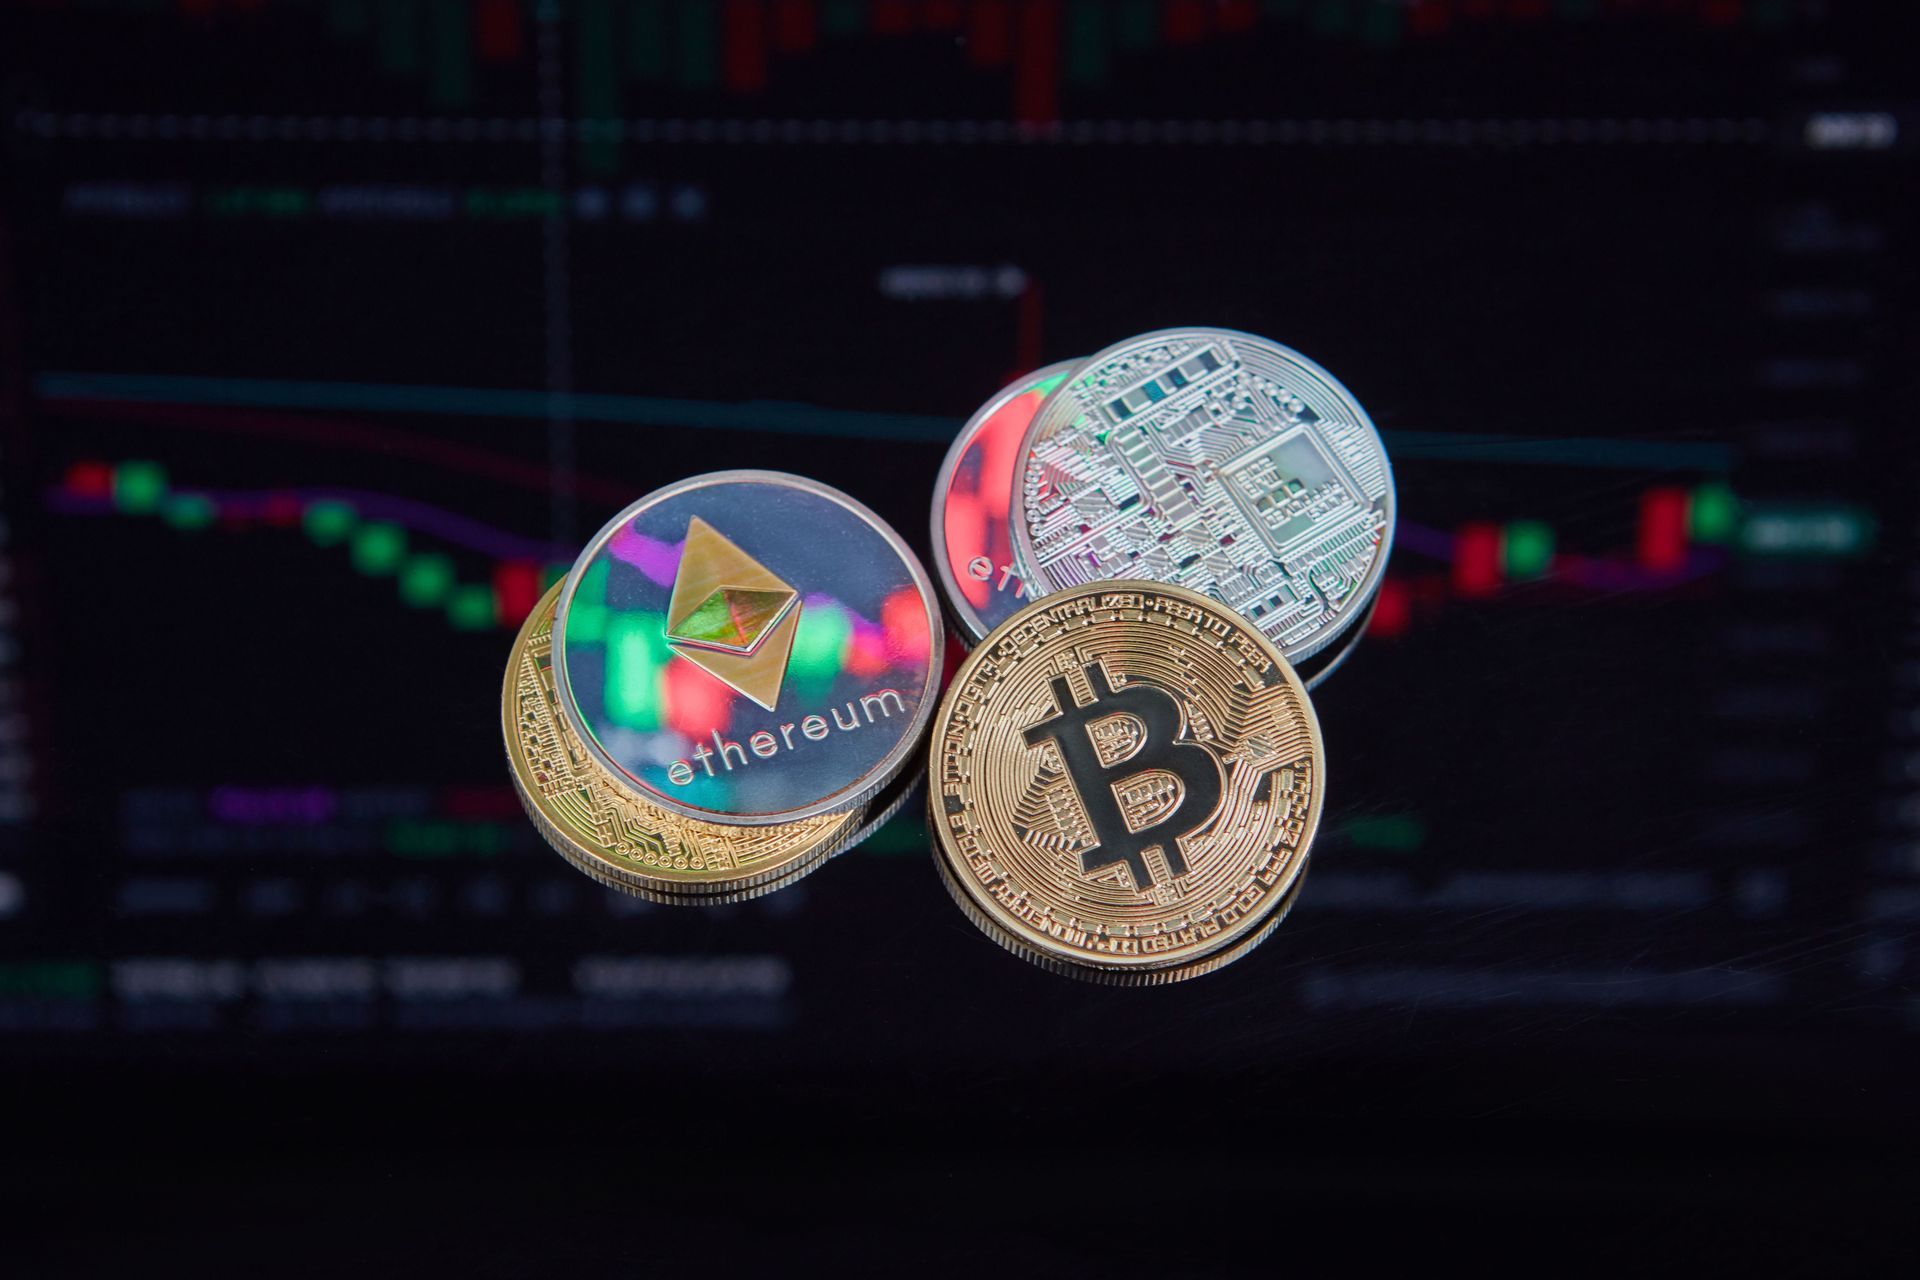
When you think about estate planning, you may picture your home, retirement savings, or possessions you hope to leave to family members. But much of everyday life now exists online. Important financial records may arrive only by email, while decades of family photographs may be stored in a cloud account. Without planning, the people handling your affairs may struggle to locate those records or obtain the authority needed to manage them. Addressing digital assets can help make your estate plan more complete. Start With an Inventory Digital assets can include electronic files and online accounts with financial or sentimental value. Your inventory might identify email accounts, cloud storage, social media profiles, cryptocurrency holdings, and websites or domain names you own. Also identify financial institutions you access online. Although the money in a bank account is distinct from the online account used to manage it, knowing where that account exists can be essential. For a small business owner, the inventory should also address business systems and records. Consider what someone would need to keep operations running if you became unavailable unexpectedly. Decide What You Want Preserved Different accounts may call for different instructions. You might want family photographs saved and shared with your children, while preferring that certain personal accounts be closed. Think about who should receive important files and whether any material should remain private. Avoid assuming that the person handling your estate will know which documents matter or where they are stored. Backing up irreplaceable photographs and other meaningful files can also reduce dependence on a single account or service. Address Legal Authority Knowing a password does not necessarily give someone legal authority to use an account. Vermont’s Revised Uniform Fiduciary Access to Digital Assets Act provides a framework for access by executors and other fiduciaries, but access depends on the circumstances and applicable requirements. Your estate planning documents should address digital assets and your wishes concerning disclosure. The contents of private electronic communications deserve particular attention because access can involve additional consent requirements. An attorney can help coordinate these provisions with the rest of your plan. Review Account Planning Tools Some providers offer online tools that allow users to direct what happens to account information after death. These settings should be reviewed alongside your legal documents. Under Vermont law, a direction made through a qualifying online tool can override conflicting instructions in a will, trust, or power of attorney. Completing estate planning documents without checking those settings may therefore leave inconsistent instructions in place. If no applicable online direction exists, your legal documents can play an important role in expressing whether disclosure should be allowed or prohibited. Keep Access Information Secure Your plan should explain where authorized individuals can find necessary access information without unnecessarily exposing it. Avoid putting passwords directly in your will, which may become part of a court record. A secure password manager or a separately maintained record may be useful, depending on your circumstances. Consider how account recovery works, particularly when verification depends on a phone or another email account. Cryptocurrency requires special care. Losing necessary keys or recovery information can make assets inaccessible, while sharing that information carelessly can expose them to theft. Keep the Plan Current An inventory becomes less useful as accounts change. Review it periodically and after significant changes to your online activities or business. Make sure the appropriate person knows that your instructions exist and where to find them. Contact Deppman Law PLC Planning for digital assets can help preserve meaningful records and give the people handling your affairs clearer guidance. To learn more about incorporating digital assets into your Vermont estate plan, reach out to Deppman Law PLC for more information.
August 14, 2026
For a small business owner, divorce can raise questions that extend well beyond the family home or joint bank accounts. A business may represent years of work and provide the income that supports both spouses. If they built or operated it together, separating their personal lives may also mean untangling their working relationship. Understanding how a business may be addressed in a Vermont divorce can help owners prepare for difficult decisions while protecting ongoing operations. Is the Business Part of the Property Division? Vermont courts have broad authority to divide property in a divorce. All property owned by either or both spouses may be considered, regardless of when it was acquired or whose name appears on the ownership documents. A business started before the marriage or inherited from a parent is therefore not automatically excluded. However, being subject to division does not mean that a business must be split equally. Vermont follows equitable distribution, which calls for a fair division based on the circumstances. Relevant considerations include the length of the marriage, each spouse’s financial situation, and their contributions to acquiring or preserving property. Nonfinancial contributions, including homemaking, also matter. Determining What the Business Is Worth Before spouses can meaningfully discuss how to address a business, they need a reliable understanding of its value. Annual revenue alone does not answer that question, and a business’s tax return may not tell the whole story. Depending on the company, a valuation may examine its assets and outstanding debts, along with its earnings history and future prospects. The business’s dependence on the owner’s personal involvement may also require careful analysis. A qualified valuation professional can help assess these issues. Even when spouses agree that one person should keep the business, disagreements about its value can make settlement difficult. Establishing a supported value provides a stronger starting point for negotiations. Can One Spouse Keep the Business? One possible resolution is for one spouse to retain the business while the other receives different assets or a negotiated payment. For example, the overall settlement might allocate a larger share of other property to the spouse who is giving up a claim to the business. That arrangement must be financially workable. A business may have substantial value without enough available cash to fund an immediate buyout. Payment terms should account for operating expenses and the company’s ability to continue generating income. Selling the business may be another option. Some former spouses consider continuing as co-owners, although that requires a realistic assessment of whether they can work together and a clear agreement governing future decisions. What If Both Spouses Work There? When both spouses are involved in daily operations, ownership is only part of the discussion. They may also need to address employment responsibilities and compensation while the divorce is pending. Consider practical questions early: Who will communicate with employees? Who can approve significant expenditures? How will financial information be shared? Temporary arrangements can help preserve stability while longer-term issues are resolved. Personal disagreements can otherwise spill into business decisions and affect relationships with customers or staff. Prepare Before Making Changes Gather financial records and any agreements affecting ownership or transfers. If other owners are involved, their rights and the company’s governing documents also need attention. Before changing compensation, transferring ownership, or making unusual withdrawals, speak with an attorney. Decisions made during a divorce can affect both the business and the property settlement. Contact Deppman Law PLC Addressing a business in divorce requires attention to the company’s future as well as each spouse’s financial needs. If you own a business and are considering divorce, or have questions about a jointly operated company, reach out to Deppman Law PLC for more information about your options.